 Retire Plan
the rules that move the number
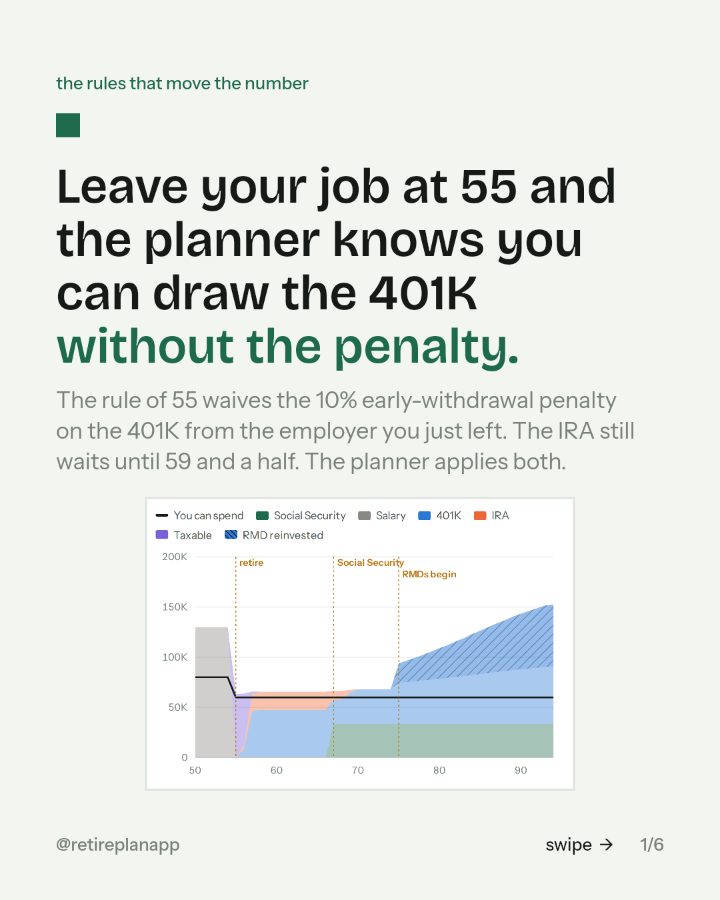
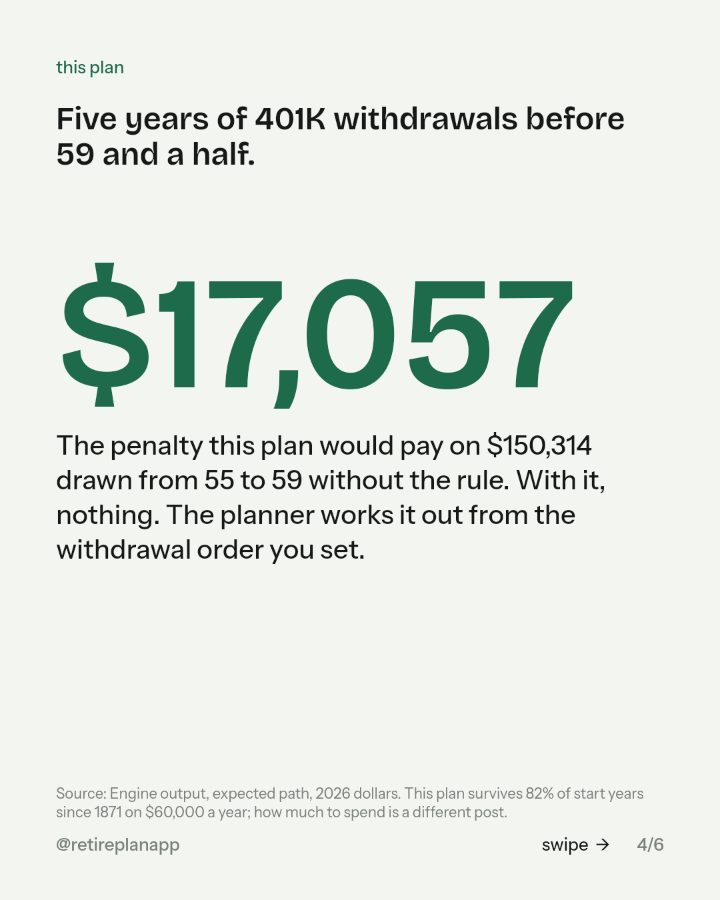
Leave your job at 55 and the planner knows you can draw the 401K without the penalty.
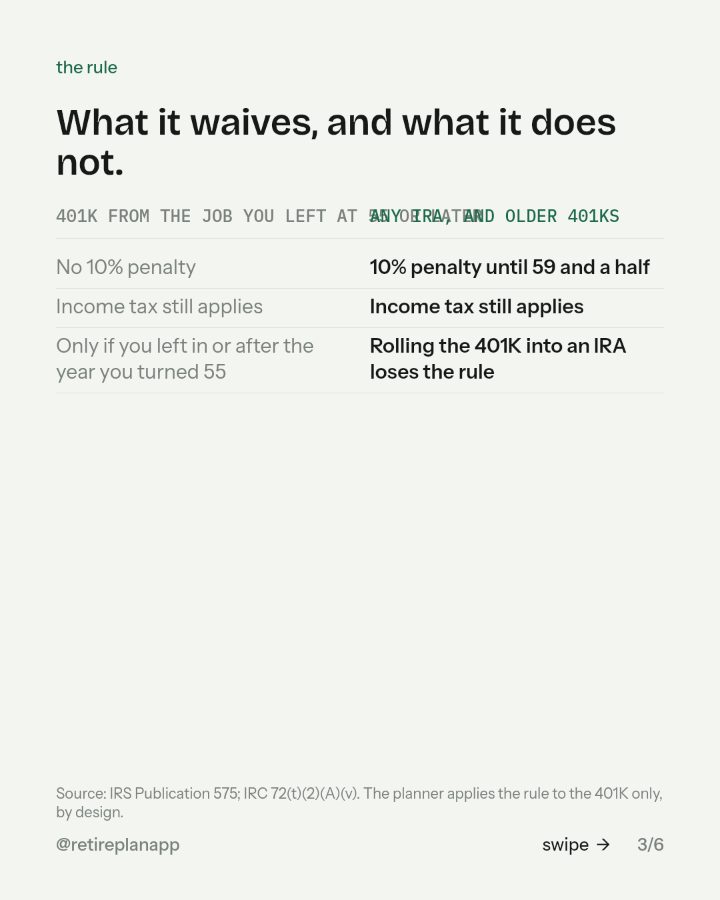
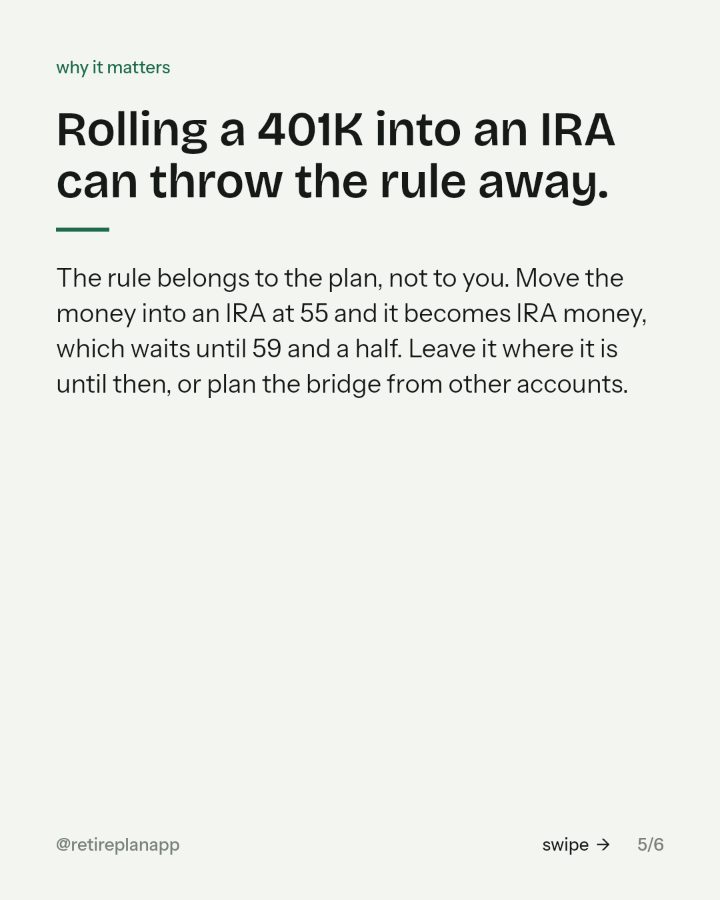
The rule of 55 waives the 10% early-withdrawal penalty on the 401K from the employer you just left. The IRA still waits until 59 and a half. The planner applies both.
You asked for the link. The planner every chart came from is one tap away; the slides are below if you want them again.
Open the planner Type in one paycheck. About three minutes, in the browser.
Where to go next
Retire Plan
Type in one paycheck and it runs your plan through every year of market history since 1871, with the taxes worked out. About three minutes, in the browser.
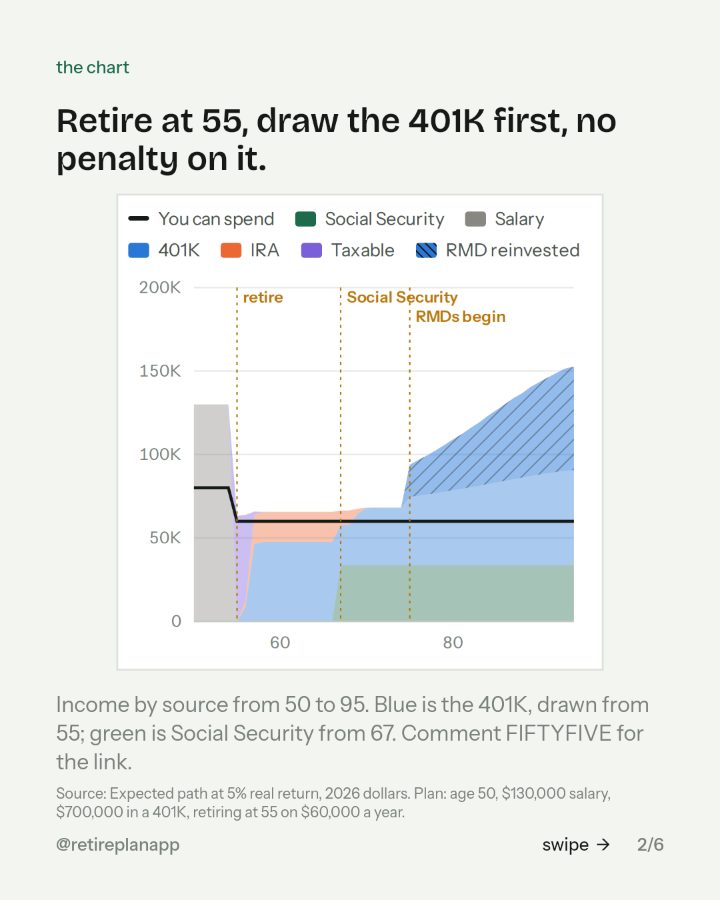
Open itSources: Expected path at 5% real return, 2026 dollars. Plan: age 50, $130,000 salary, $700,000 in a 401K, retiring at 55 on $60,000 a year.; IRS Publication 575; IRC 72(t)(2)(A)(v). The planner applies the rule to the 401K only, by design.; Engine output, expected path, 2026 dollars. This plan survives 82% of start years since 1871 on $60,000 a year; how much to spend is a different post..