 Retire Plan
what history actually did
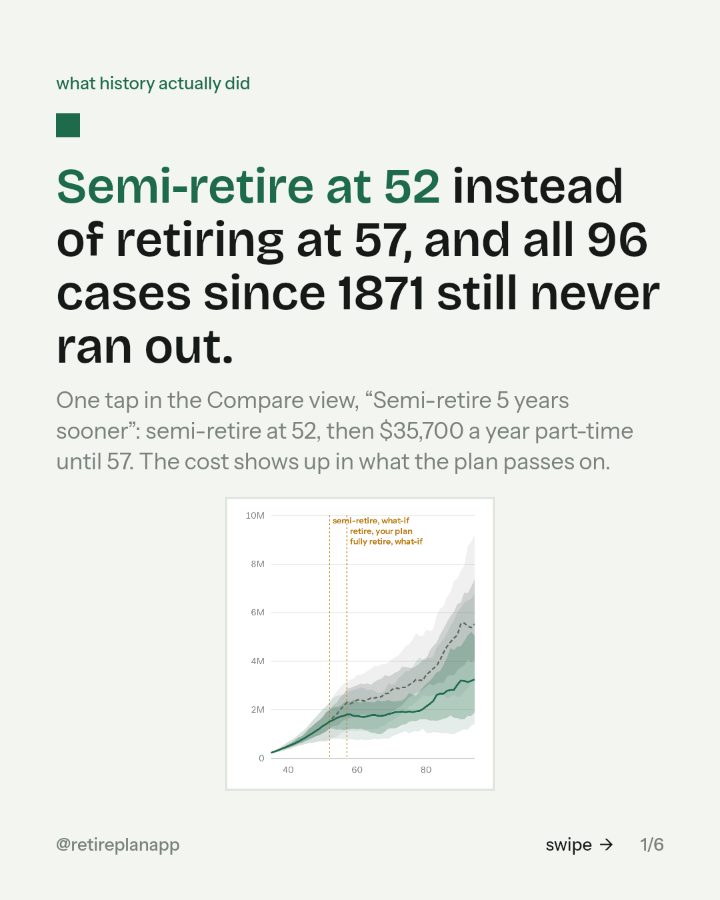
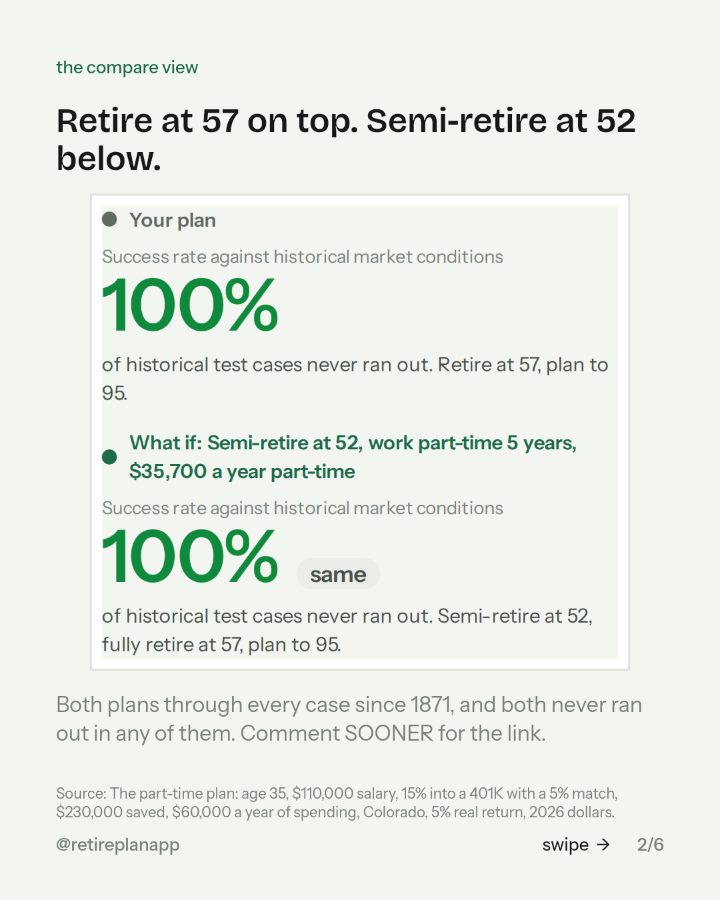
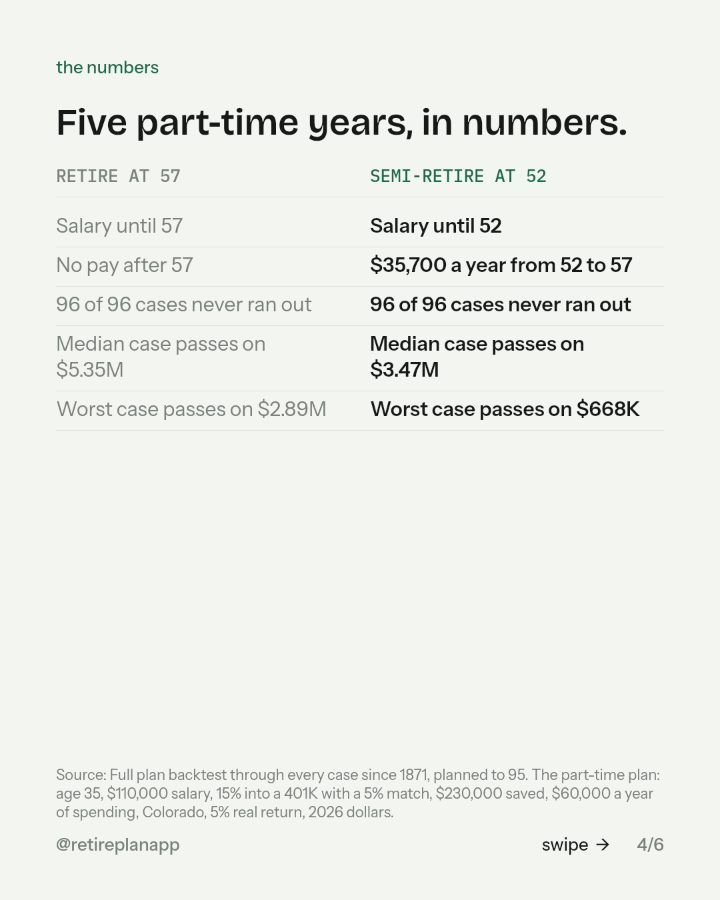
Semi-retire at 52 instead of retiring at 57, and all 96 cases since 1871 still never ran out.
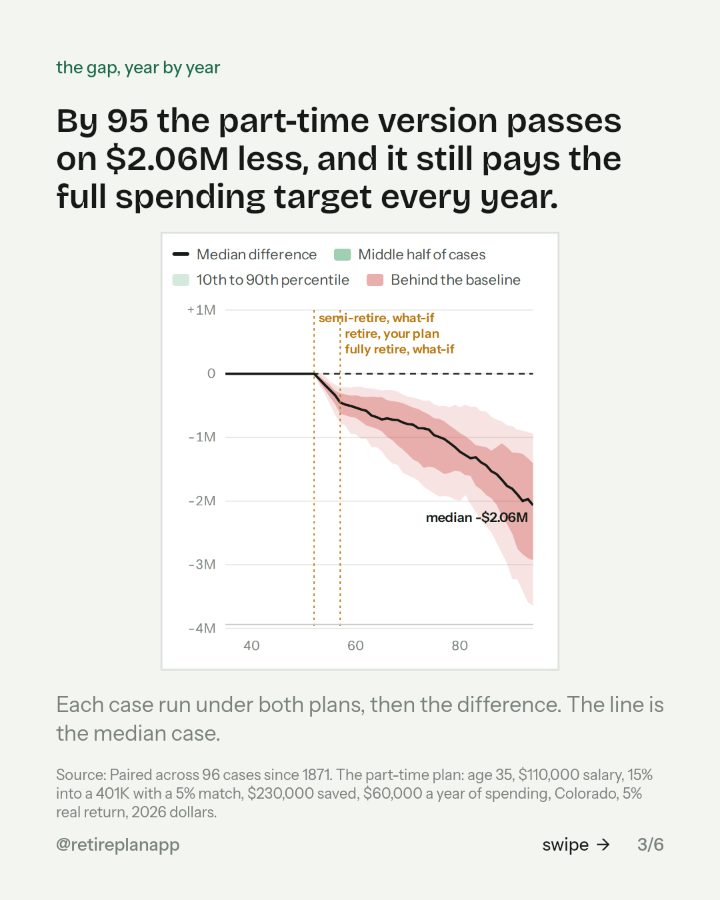
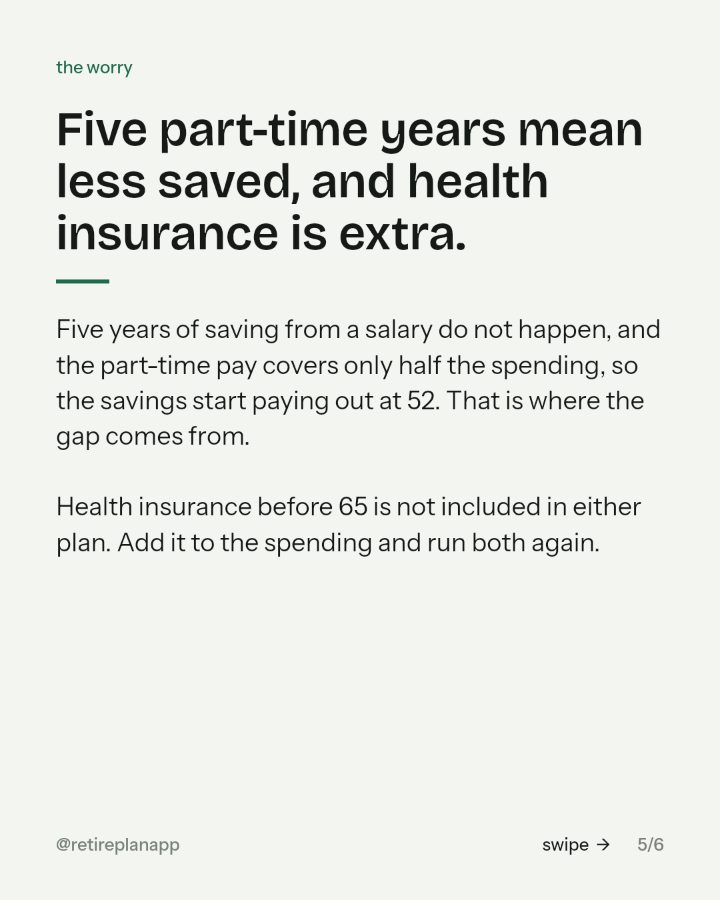
One tap in the Compare view, “Semi-retire 5 years sooner”: semi-retire at 52, then $35,700 a year part-time until 57. The cost shows up in what the plan passes on.
You asked for the link. The planner every chart came from is one tap away; the slides are below if you want them again.
Open the planner Type in one paycheck. About three minutes, in the browser.
Where to go next
Retire Plan
Type in one paycheck and it runs your plan through every year of market history since 1871, with the taxes worked out. About three minutes, in the browser.
Open itSources: The part-time plan: age 35, $110,000 salary, 15% into a 401K with a 5% match, $230,000 saved, $60,000 a year of spending, Colorado, 5% real return, 2026 dollars.; Paired across 96 cases since 1871. The part-time plan: age 35, $110,000 salary, 15% into a 401K with a 5% match, $230,000 saved, $60,000 a year of spending, Colorado, 5% real return, 2026 dollars.; Full plan backtest through every case since 1871, planned to 95. The part-time plan: age 35, $110,000 salary, 15% into a 401K with a 5% match, $230,000 saved, $60,000 a year of spending, Colorado, 5% real return, 2026 dollars..